Vacant property insurance between owners, tenants, and projects
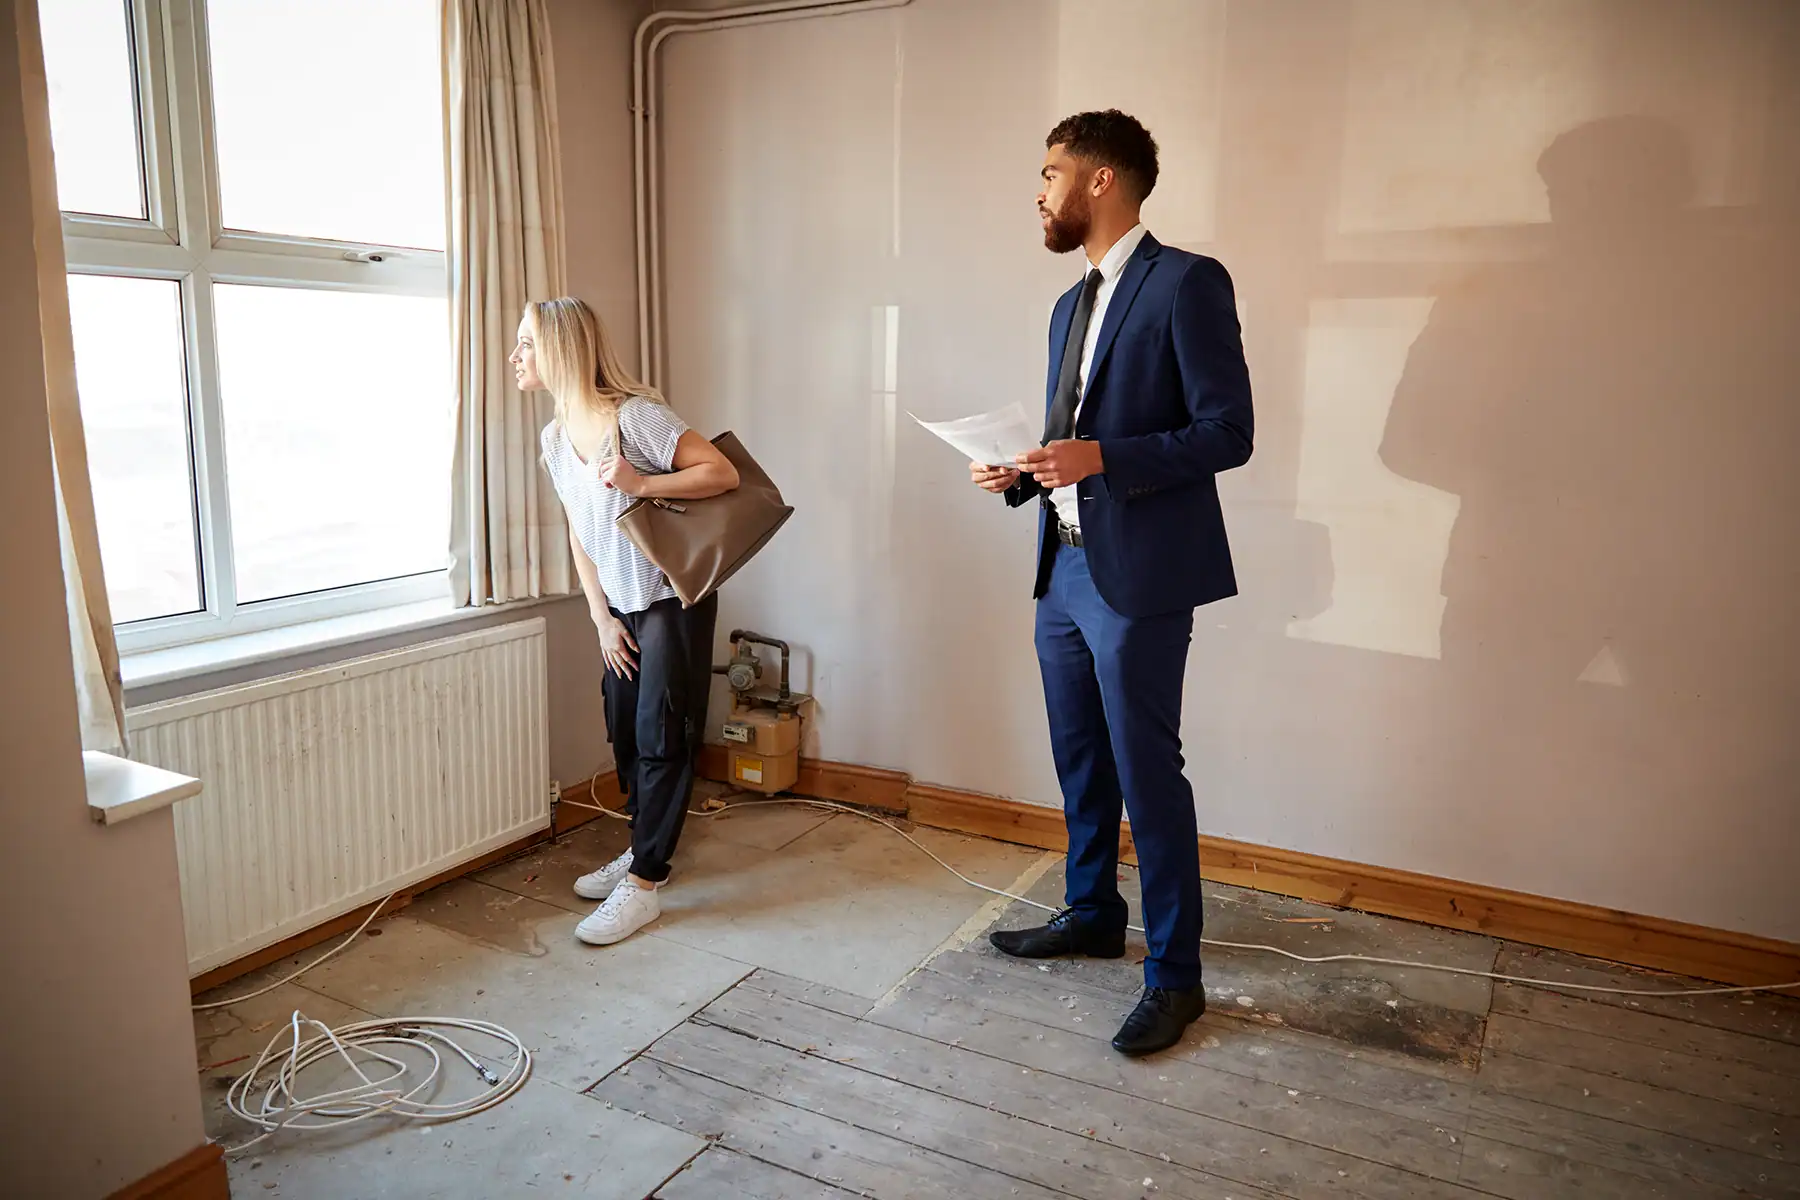
An empty property can be at higher risk for theft, vandalism, and undetected damage, and many standard policies limit coverage once a property has been vacant for a period of time.
Many homeowners and landlord policies restrict or exclude certain losses when a property has been vacant beyond a set period, often 60 consecutive days. Vacant dwelling or vacant building policies are designed for these situations.
Tell us how long the property will be empty, whether utilities are on, and whether work is planned. Those details shape your options.
At a glance
Vacant dwellings and buildings
Fire, wind, and other covered perils
Vandalism and theft options vary
Liability options
Short or long vacancy periods
What it can help cover
Common vacant property situations
Just purchased
Closed on a property and work has not started yet.
Between tenants
Turnover and make-ready periods.
Listed for sale
Empty while on the market.
Inherited homes
Property waiting on an estate decision.
Pre-renovation
Before builders risk or renovation coverage begins.
Often a vacant dwelling policy or a vacancy endorsement, because standard policies can limit coverage after a period of vacancy. Tell us the expected timeline and plans.
Some vacant policies allow limited renovation work; larger projects may call for builders risk or a renovation policy. We will help you match the policy to the plan.
Investors and builders
Discuss your property
Share the basics about the property and your plans. Please keep financial and underwriting documents for a secure follow-up. We will tell you what we need.
Your request goes to Jana Baker, who works closely with real estate investors and builders.
Coverage and bond availability are subject to underwriting and applicable policy or bond terms, conditions, and exclusions. Requesting a quote or submitting a form does not bind or change coverage or issue a bond.